
8 Home Insurance Claim Adjuster Secret Tactics
For the video rendition of this article see below. If you favor to peruse, continue scrolling down for the blog entry.
Home Insurance Claim Adjuster Secret Tactics: Explainer Video
Steven Pollack was able to secure reasonable attorney fees and insurance benefits based on the bad faith litigation, after the insurance company denied the claim of the insured who had missed a premium payment.
Home Insurance Claim Adjuster Secret Tactics: Blog Post
Familiarizing yourself with the insurance company’s claim adjusters’ secret tactics is a way of arming your defenses against their attempts to pay out a lower settlement than you deserve.
According to Ancient Chinese general Sun Tzu, “Understand your adversary…”.
It’s important to remember that the tactic our friend brings to us is not the same as being their friend, so you shouldn’t think of your insurance company as exactly that.
Pretending To Be Your Friend
When you first contact the insurance company, you may find yourself on the side of an adjuster who mistakenly believes that you may be led into tactics of the home insurance claim. It is important to note that this is one of the secret tactics used by adjusters. Typically, the adjuster is very accommodating and friendly during this initial contact, which is often referred to as a honeymoon period with the insurance company.
If you are thinking about hiring a lawyer and being contacted by public adjusters, it is important to know that the adjuster is aware of this. Unlike the homeowner, the insurance company typically has professional representation, which often leads to more effective negotiation of a home insurance claim.
Often, I hear people wanting help with their claim during this period. It is indeed a very short honeymoon, and this special time does not always last.
Bullying
After the initial phase of marital bliss, bullying emerges as one of the covert strategies employed by home insurance claim adjusters.
The adjuster may become overly harsh or rude with you, knowing that you are sensitive and that your claim may result in some type of error or a devastating loss, which could make you frustrated and angry.
If the adjuster provokes you successfully, they will know that getting out of jail free card in the litigation case will cause them to act unprofessionally and aggressively, rather than being cooperative.
If you are considering hiring a professional lawyer for property damage insurance, you should seriously consider the signs of aggressive behavior from the insurance adjuster. No matter how strong you think you are, if the adjuster shows any aggressive behavior, they will try to negotiate the insurance claim under adversarial circumstances for a long time.
Request for Recorded Statement or Financial Documents
Requesting recorded statements or financial documents is one tactic used by home insurance adjusters to investigate and adjust your claim, so you can either claim or deny their attempt to keep their investigation methods secret.
Legally, you are under no obligation to furnish the insurance company with anything beyond what you are mandated to adhere to. It would be advisable to review your policy or seek assistance from an insurance attorney to examine it on your behalf, as your insurance policy specifies the level of compliance required for these inquiries.
They will later assert that they have proof of misrepresentation, incorrectly answering you if you’re unsure about things and asking questions. The insurance company may use the recorded statement during which you may ask questions to show that you are in financial distress and accuse you of causing your own loss, therefore they may try to use financial documents to demonstrate this.
Having an insurance lawyer can be extremely helpful in this phase, as they can send information to the insurance company, encouraging them to settle before necessary litigation. It shows action to the adjustor that you know what they are up to and that you are not messing around, even before they show their counters and theories.
If you have more time to review, I will inform you of the answers to your questions and provide you with supplementary information. It is important to remember that if you are unable to recall all of the information, it is better to disclose less rather than more. If you choose to go alone during an examination or a recorded statement, be prepared to disclose all of your income and expenses under oath.
The insured’s attempt to misrepresent the condition of their financial situation was an effort to claim later and the insurer has been both lost and won cases due to the insured’s failure to disclose many credit cards.
Repairing Instead Of Replacing
Insurance adjusters prefer to repair whenever feasible, as it is a more cost-effective alternative to replacing a damaged item. It is crucial to acknowledge this as one of the secret tactics employed by home insurance claim adjusters before it becomes a problem.
Typically, insurance policies state that the insurance company is responsible for repairing or replacing an item of lesser quality in a form that is similar in quality and kind, knowing that you may feel pressured to accept this repair due to the battle with your insurance company wearing you down.
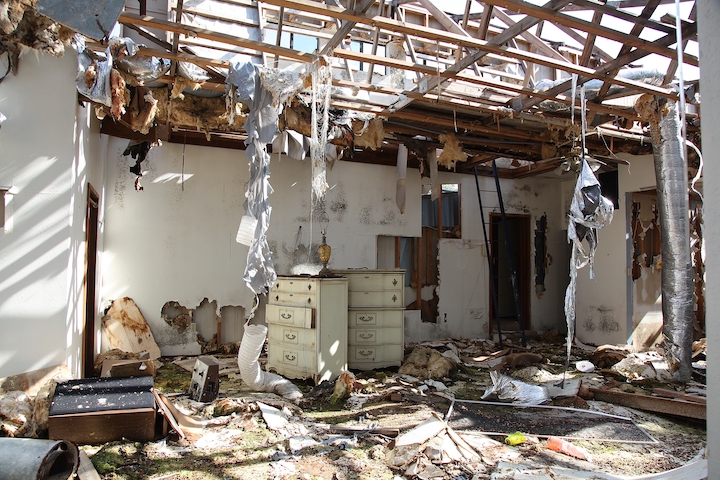
This information will not reveal the insurance provider, however, it could render the roof more vulnerable to potential leaks compared to its original state if only the damaged section is replaced instead of replacing the entire roof in the event of a fire, for instance.
The company cleaning did not take any responsibility for the failed attempt, and neither did the company insurance. If the repairs are not successful, you may lose a significant amount of coverage. At the same time, the cleaning company asks you to sign a contract acknowledging that there is no guarantee for the return of your clothes in their prior condition. Meanwhile, the insurance company may try to use thousands of dollars from your coverage to send out your smoke-damaged clothes for cleaning.
It is a significantly improved approach. Occasionally, the insurance company may consent to merely cleanse a small portion as a trial to assess the cleanability of the smoke damage. If neither party agrees, then politely decline the offer to attempt cleaning at your own risk. Secondly, kindly request the cleaner to ensure their cleaning services, so they agree not to charge for any unsuccessful attempts. First and foremost, I suggest asking the insurance company to guarantee the attempt, so in case of failure, you will still have the same level of coverage.
Using Additional Living Expense as Pressure
If your property experiences damage or a fire, most home insurance policies require you to cover the additional expenses for living elsewhere.
Some adjusters may suggest staying in a hotel while your house is being repaired if you have previously lived in a similar home and it would be easier for them.
In order to acknowledge their claim approximation, your insurance provider could potentially attempt to coerce you to vacate your interim accommodations as a forceful method if you encounter disputes with the insurance company that impede the commencement of repairs on your residence.
The negotiation process with your insurance company can be critical at this stage, as they must understand that you need to start working in order to cover your additional living expenses until they agree to settle on a fair settlement. It is important to note that your policy states that the company will only cover reasonable living expenses for the required amount of time during construction. In helping to make this process faster, it may be beneficial to involve a lawyer.
Ignoring You
Many people are aware of the sneaky tactics used by home insurance claim adjusters, so it is not surprising that their customers completely disregard the insurance companies’ policies.
They don’t reply, however, you leave a message and send an email, and they are unavailable when you contact them. In certain instances, disregarding your attempts to reach them benefits the adjuster because the claimant becomes extremely desperate to receive their money, leading them to accept a payment that is less than satisfactory.
Illinois regulations state that insurance companies must respond to pertinent communications within a reasonable period, which is deemed to be 15 days.
Ultimately, without any dispute, they eventually agreed to acknowledge our assertion. They were simply anticipating if they could dismiss us by disregarding our requests, but nearly instantly the insurance company replied, consenting to fully compensate the claim. Following more than a year of being disregarded by the insurance company, I initiated legal action on behalf of my client in a particular instance.
Steven Pollack was able to step in and immediately obtain full coverage by simply filing a lawsuit, after the life insurance company delayed payment of the claim for over a year by asserting an ongoing investigation.
Underestimating and Over Depreciating
The ongoing underestimation by insurance firms of the worth and expense of repairing lost or damaged belongings is a sneaky approach that ought to be listed among all the undisclosed tactics of home insurance claim adjusters.
It is important to note that there is absolutely no provision policy telling them to make the estimate of repair costs. The policy states that it is the responsibility of the policyholder to provide proof of loss. After property damage, insurance companies will create their own estimate of repair costs.
If insurance companies do not have an imperative reason, that is why they guess that forcing you to fight for every penny, accepting lower claims, and resolving them will eventually lure you away and save them money by lowballing costs over time.
Xactimate is often used by contractors to create estimates that reflect the updated costs of building materials. However, Xactimate may not always accurately account for the actual cost of drywall, as it assumes that only 4×8 sheets of drywall can be purchased, despite the fact that drywall can be bought in different sizes. Additionally, Xactimate is a software often used by insurance companies to estimate the cost of building materials, but it does not take into account any waste or additional materials needed for the construction process. Therefore, contractors who use Xactimate may not always agree with the estimates it produces, as it is not an exact representation of the actual work required.
Insurance adjusters often claim high percentages of depreciation on items, regardless of the actual amount by which the item has depreciated. Even if the item was in perfect condition at the time of the fire, adjusters may assert that an item that is eight years old and has a useful life of ten years has lost 80% of its value.
In such circumstances, insurance attorneys can assist in defending the rights of policyholders. However, insurance providers can be exasperating, disputing minor specifics such as the pre-accident or pre-fire condition of an object, which can be challenging to substantiate. This disregards the residual worth of an object at the conclusion of its presumed useful lifespan, and the insurance company asserts a zero actual cash value when an object surpasses its stated useful lifespan. Such occurrences frequently arise.
Lying
It is not uncommon for insurance adjusters to misrepresent what your policy covers, especially during an in-person meeting or an unrecorded phone call. They will not be held accountable for their actions.
I have seen many clients who were surprised when they found out that the insurance company’s adjuster told them it wasn’t covered. If there was misrepresentation in the writing, the adjuster will certainly deny it. As an insurance lawyer, I will almost certainly make adjustments to ensure that it is not covered.
The reason this strategy is effective is because the policyholder ceases to assert a claim for that particular item, resulting in the absence of any written record indicating that a claim was ever made for it. As a result, there is also no written record indicating that it was officially denied.
In the event of a legal dispute, evidence of the adjuster’s deceptive statements can be utilized as a means to challenge them. By obtaining proof of the adjuster’s misrepresentations, my clients can prevent the adjusters from denying their statements or, alternatively, recapitulate the conversation via email after a verbal exchange. I strongly advise my clients to maintain written communication with the insurance company whenever feasible.
Conclusion
I can assist you today in figuring out how to fill out my form for a completely free consultation to determine how I can help. Unless you want to be paid, you don’t have to pay, which means you can hire an insurance lawyer who will work for you on a contingency basis to ensure you get a fair settlement. Familiarizing yourself with the secret tactics of insurance claim adjusters is the best way to step in the right direction and ensure you get a fair settlement.