Life insurance is a type of coverage that provides 100% coverage for your death, whether it is accidental or natural, with no waiting period. This insurance includes burial and life insurance, and it requires you to make the payment first.
In simpler terms, you do not need to wait for a duration of two years before you are provided with coverage.
Whether you believe it or not, numerous providers offer these plans.
Explore ways to fulfill the criteria for immediate coverage and obtain free quotes from leading life insurance companies that provide this type of safeguard.
What Is A Partial Waiting Period?
In the initial two years, merely a fraction of the payout will be disbursed as the death benefit, frequently known as a “graded plan,” involving a limited waiting period.
It’s common for partial plans to have a payout that is 30%-40% during the first 12 months. Then during months 13-24, the payout is typically 50%-75%.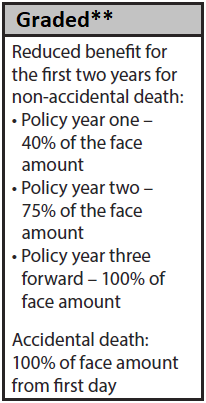
The precise payout amounts vary based on the company. The image to the right shows an example of a partial coverage policy.
Besides the partial waiting duration, the company will impose additional fees on you due to your classification as a higher-risk individual. Life insurance plans that include a partial waiting period also require a greater premium payment.
While you may not be eligible for an immediate benefit type of life insurance, you may just qualify for a partial plan.
And just like a no waiting period burial insurance policy, partial coverage options still require you to answer health questions to qualify.
Limited coverage plans are typically policies that do not require a medical examination, but there are inquiries regarding one’s well-being.
What Is Burial Life Insurance With No Waiting Period?
In the initial two years, in the event of a demise, a life insurance plan that has no waiting period will provide the full death benefit, regardless of whether it is for covering funeral expenses or other financial obligations.
Death can happen as a result of either natural or accidental causes, and your beneficiaries will still receive the full amount of benefits upon demise.
Tip:.
According to insurance experts, collaborating with an independent life insurance agent, as opposed to purchasing directly from an insurer, is the most effective method to be eligible for a plan with no waiting period. Individuals with health issues have the option to obtain this kind of policy from numerous life insurance companies. It is not necessary to be in excellent physical condition in order to meet the requirements for an immediate coverage plan.
Despite previous health concerns, the majority of individuals are eligible for a “first-day coverage” scheme that provides insurance beyond accidental death.
It’s usually just a matter of searching until you find a life insurance company that will accept all your health conditions and insure you immediately.
How to qualify for no waiting period final expense insurance
In order to qualify for the final health insurance expense, you must apply with a company where you are subsequently approved, and there is no waiting period. Additionally, you are required to answer health-related questions.
You don’t need to go through a medical examination, but you are required to respond to certain medical inquiries.
Keep in mind that life insurance plans without health inquiries always have a two-year waiting period (excluding accidental death).
Eligibility For Each Medical Condition
The chart provided below outlines health concerns and their eligibility for life insurance without a waiting period.
Please keep in mind that your age and location may lead to a varied result.
Additionally, not all insurance offerings are accessible to individuals of every age or in all states.
That being said, this list is quite reliable for the majority of individuals in the United States seeking insurance.
The deficiency of choices in NY is significant. Only a handful of businesses provide coverage in that area. New York is the sole state where this roster will not be highly precise. The issue with NY is.
| Health Condition | Eligibility | Health Condition | Eligibility |
|---|---|---|---|
| Alzheimer’s
disease |
Waiting period | Amputation due
to disease |
<2 Yrs: Waiting period
>2 Yrs: Immediate |
| Angina (chest pains) | Immediate | Anxiety | Immediate |
| Arthritis | Immediate | Assistance with activities
of daily living (ADL’s) |
Immediate |
| Asthma | Immediate | Atrial fibrillation
(Afib) |
Immediate |
| Bipolar disorder | Immediate | Blindness | Immediate |
| Blood clots | Immediate | Blood
thinners |
Immediate |
| Bone marrow
transplant |
Waiting period | Cancer
(except basal or squamous) |
<2 Yrs: Waiting period
>2 Yrs: Immediate |
| Circulatory/heart surgery | <1 Yrs: Waiting period
>1 Yrs: Immediate |
High cholesterol | Immediate |
| Chronic bronchitis | Immediate | Chronic kidney
disease (no dialysis) |
Immediate |
| Cirrhosis | Immediate | Congestive heart
failure (CHF) |
Full waiting period |
| COPD | Immediate | Covid | Immediate |
| Crohn’s disease | Immediate | Cystic fibrosis | Immediate |
| Defibrillator | Installed <1 Yr: Waiting period
Installed >1 Yr: Immediate |
Dementia | Waiting period |
| Depression | Immediate | Diabetes (Type 1) | Immediate |
| Diabetes (Type 2) | Immediate | Diabetic coma | <2 Yrs: Waiting period
>2 Yrs: Immediate |
| Diabetic nephropathy | Waiting period | Dialysis. | Waiting period |
| Emphysema | Immediate | Enlarged prostate | Immediate |
| Epilepsy | Immediate | Fibromyalgia | Immediate |
| Graves disease | Immediate | Heart attack | <1 Yr: Waiting period
>1 Yr: Immediate |
| Hepatitis A | Immediate | Hepatitis B | Immediate |
| Hepatitis C | Immediate | High blood
pressure |
Immediate |
| Home health
care |
Immediate | Insulin shock | <2 Yrs: Waiting period
>2 Yrs: Immediate |
| Insulin usage | Immediate | Lupus | Immediate |
| Mini stroke
(TIA) |
Immediate | Multiple sclerosis | Immediate |
| Nephropathy | Waiting period | Neuropathy | Immediate |
| Obesity | Immediate | Organ transplant | Waiting period |
| Oxygen equipment
(except for sleep apnea) |
Waiting period | Pacemaker | Installed <1 Yr: Waiting period
Installed >1 Yr: Immediate |
| Pancreatitis | Immediate | Parkinson’s disease | Immediate |
| Retinopathy | Immediate | Rheumatoid arthritis | Immediate |
| Schizophrenia | Immediate | Seizure issues | Immediate |
| Sickle cell anemia | Age 0-49: Waiting Period
Age 50+: Immediate |
Sickle trait | Immediate |
| Sleep apnea | Immediate | Stroke (Non TIA) | <1 Yr: Waiting period
>1 Yr: Immediate |
| Systemic lupus | Immediate | Transient ischemic
attack (TIA) |
Immediate |
| Tumors (cancerous) | <2 Yrs: Waiting period
>2 Yrs: Immediate |
Tumors (noncancerous) | Immediate |
| Ulcerative colitis | Immediate |
Health Issues Where You Will 100% Have A Waiting Period
Regrettably, certain medical conditions pose such a significant risk that no insurance provider will provide immediate or partial coverage.
Irrespective of your actions, a waiting period of two years will be applicable if you possess any of these conditions in your medical records.
There might be additional circumstances as well, but this comprises the majority of them.
As you read the list, you will notice that there are many chronic illnesses that are not listed. Earlier in this article, it was mentioned that most of these conditions can be insured.
It is strongly advised to consult with a qualified and licensed representative who can evaluate your eligibility for instant or restricted coverage.
How Does The “Contestability Clause” Work?
Life insurance that offers complete or partial protection within the initial two years will still include the contestability provision.
The contestability clause grants the insurer the right to investigate death claims within the first two years (it’s one year in some states).
Prior to disbursing the claim to your dear ones, the insurance company will request all of your medical documents.
Their objective is merely to ascertain whether the candidate was honest regarding their well-being during the application process.
Tip:.
It is impossible to avoid this clause in a life insurance contract, as all insurance companies in the USA include this provision. Some companies employ deceptive marketing tactics to give the impression that this provision does not exist, but it does. For instance, Lincoln Heritage advertisements often declare, “Approved claims paid in 24 hours.” However, the crucial word “approved” is often overlooked by most people. The Lincoln Heritage Funeral Advantage death claims that occur within the first two years will only be “approved” after the contestability clause is exercised.
If your medical records demonstrate that you had a condition that can be denied coverage at the time of your application, your claim will not be reimbursed. However, they will cancel the policy and reimburse the premiums you have paid.
They will pay the full death benefit if your medical records confirm that you didn’t have any declinable conditions when you applied.
It is imperative to remember that the insurance company will not be concerned with any medical issues that arose subsequent to the submission of your application.
The only concern they have is your medical background when you applied. Your health after the policy was issued is not important.
Honestly, disputed assertions are uncommon, and the majority lead to a complete compensation.
However, there are some claim rejections because the insurance company discovered that the applicant legitimately did not meet the requirements initially.
Take a look at this sample clause on contestability from an authentic policy to see how it is written.
Keep in mind that you can obtain burial insurance with no waiting period, but it will still include the contestability clause.
How Do Guaranteed Acceptance Life Insurance Policies Work?
The process of applying for a life insurance policy does not require you to answer lifestyle or health-related questions or take an exam. The insurance company does not issue a guaranteed policy underwriting requirement.
In simple terms, your acceptance is assured because your medical background does not dictate your qualification.
It is crucial to comprehend that all guaranteed acceptance policies require a mandatory waiting period of two years, during which the insurer will solely reimburse the premium payments if the policyholder passes away.
A guaranteed issue life insurance policy will still pay out the full coverage amount in the first two years if you die from an accident. The waiting period rule has one exception, which is for accidental death.
In general, guaranteed issue coverage will typically be a whole life insurance policy.
Life term insurance is guaranteed to exist, but it is quite scarce. There is still a waiting period for it (guaranteed issue life term insurance). The insurance rates increase every five years, and there is no cash value in the policy term. Additionally, the policy expires at the age of 75.
Is there guaranteed acceptance with no waiting period?
There is no such thing as no health questions and no waiting period. All guaranteed issue policies have a two-year waiting period.
Unfortunately, certain companies will deceive and create the illusion that you can obtain a policy without any inquiries or waiting period.
If there existed a policy that was not underwritten and provided immediate coverage, every hospice patient would purchase it.
The insurance corporation would go bankrupt within a month.
Tips For Getting Full First-Day Coverage
During the initial two years, you have the opportunity to implement certain pragmatic measures in order to increase your odds of obtaining a comprehensive senior life insurance policy.
The objective is to locate an insurance company that has underwriting accepting of all your medical conditions.
The best way to find an independent insurance broker is to work with multiple insurance companies, such as Mutual Choice, who partner with independent agencies that benefit the policyholders.
They will grant you approval promptly, if they ascertain the underwriting of each individual. On your behalf, numerous policies are compared to provide you with the freedom.
If your single company does not approve you, you will not have any alternative options. Dealing with a captive agent (who represents only one insurer) means they are unable to explore multiple companies on your behalf.
The same holds true when working directly with an insurance company like Colonial Penn, TruStage, or Globe Life.
If they don’t approve you (something that those three companies rarely do), they definitely won’t make an effort to search for another insurance provider for you.
Tip:.
Working with an independent life insurance agent doesn’t cost you anything more, as they are not used as “middlemen” by insurance companies to charge you for their services. Additionally, the insurance brokers paid by the companies do not make the insurance more expensive.
If you have encountered challenges in locating burial insurance without any delays, please contact us at 1-800-644-2926.
We have assisted numerous clients in obtaining coverage on the first day, even when they believed it was otherwise unattainable.
If you want to gain more knowledge about us, you can refer to our previous customer feedback.
The 10 Best No Waiting Period Burial Insurance Companies
Many companies that provide final expense life insurance offer life insurance with no waiting period.
One company, specifically, cannot be the top choice for everyone as they each approve and decline various health conditions.
However, companies such as Mutual of Omaha, Transamerica, AIG, and Aetna (to mention a few) have extremely assertive underwriting practices.
They all accommodate a wide range of health conditions as opposed to the majority of other carriers.
If you desire additional life insurance quotes beyond those displayed in the table, kindly utilize our personalized insurance quote tool.
You’ll find prices from several carriers in your state.
| Insurance
Company |
Cost Estimates
Female Non Tobacco User $10,000 Coverage |
Cost Estimates
Male Non Tobacco User $10,000 Coverage |
Coverage & New
Applicant Age Limits |
Policy Type, Length
& Product name |
|---|---|---|---|---|
 |
$24.31 @ Age 50
$32.87 @ Age 60 $53.24 @ Age 70 $98.43 @ Age 80 |
$30.68 @ Age 50
$43.76 @ Age 60 $74.61 @ Age 70 $139.73 @ Age 80 |
Coverage:
$2,000-$40,000 Age Range: 45-85 |
Whole Life Insurance
Lasts forever once issued “Living Promise”- Level (no waiting period) |
 |
$27.30 @ Age 50
$40.51 @ Age 60 $58.19 @ Age 70 $101.41 @ Age 80 |
$34.39 @ Age 50
$51.10 @ Age 60 $73.15 @ Age 70 $140.26 @ Age 80 |
Coverage:
$2,000-$50,000 Age Range: 40-89 |
Whole Life Insurance
Lasts forever once issued “Accendo”- Preferred (no waiting period) |
 |
$35.45 @ Age 50
$39.95 @ Age 60 $58.25 @ Age 70 $118.35 @ Age 80 |
$41.35 @ Age 50
$51.85 @ Age 60 $77.75 @ Age 70 $160.05 @ Age 80 |
Coverage:
$7,000-$30,000 Age Range: 50-80 |
Whole Life Insurance
Lasts forever once issued “SIWL” (no waiting period) |
 |
$26.05 @ Age 50
$37.22 @ Age 60 $54.63 @ Age 70 $122.10 @ Age 80 |
$32.00 @ Age 50
$47.06 @ Age 60 $74.53 @ Age 70 $151.35 @ Age 80 |
Coverage:
$5,000-$35,000 Age Range: 50-85 |
Whole Life Insurance
Lasts forever once issued “PlanRight”- Preferred (no waiting period) |
 |
$24.23 @ Age 50
$32.71 @ Age 60 $52.88 @ Age 70 $101.26 @ Age 80 |
$30.55 @ Age 50
$43.49 @ Age 60 $69.78 @ Age 70 $136.34 @ Age 80 |
Coverage:
$1,000-$30,000 Age Range: 45-85 |
Whole Life Insurance
Lasts forever once issued “Immediate Solution”- Preferred (no waiting period) |
 |
$30.95 @ Age 50
$37.68 @ Age 60 $60.93 @ Age 70 $100.10 @ Age 80 |
$36.32 @ Age 50
$47.57 @ Age 60 $81.38 @ Age 70 $149.76 @ Age 80 |
Coverage:
$1,500-$35,000 Age Range: 50-80 |
Whole Life Insurance
Lasts forever once issued “New Vista”- Level (no waiting period) |
 |
$26.42 @ Age 50
$35.83 @ Age 60 $58.24 @ Age 70 $107.93 @ Age 80 |
$33.43 @ Age 50
$47.82 @ Age 60 $81.75 @ Age 70 $153.38 @ Age 80 |
Coverage:
$5,000-$35,000 Age Range: 50-80 |
Whole Life Insurance
Lasts forever once issued “SimpliNow Legacy” (no waiting period) |
 |
$34.08 @ Age 50
$41.34 @ Age 60 $65.60 @ Age 70 $135.12 @ Age 80 |
$39.97 @ Age 50
$52.16 @ Age 60 $86.49 @ Age 70 $172.93 @ Age 80 |
Coverage:
$5,000-$30,000 Age Range: 50-85 |
Whole Life Insurance
Lasts forever once issued “Eagle Premier”- Level (no waiting period) |
 |
$25.57 @ Age 50
$34.67 @ Age 60 $54.79 @ Age 70 $109.16 @ Age 80 |
$30.51 @ Age 50
$45.80 @ Age 60 $73.31 @ Age 70 $146.80 @ Age 80 |
Coverage:
$3,000-$40,000 Age Range: 50-80 |
Whole Life Insurance
Lasts forever once issued “SIMPL”- Preferred (no waiting period) |
 |
$26.67 @ Age 50
$38.27 @ Age 60 $60.39 @ Age 70 $113.69 @ Age 80 |
$31.65 @ Age 50
$47.06 @ Age 60 $78.80 @ Age 70 $155.83 @ Age 80 |
Coverage:
$2,500-$35,000 Age Range: 50-85 |
Whole Life Insurance
Lasts forever once issued “Senior Choice”- Immediate (no waiting period) |
Burial Insurance Vs. Life Insurance
Burial insurance is a promotional phrase that pertains to a particular type of entire life insurance intended to offer protection for funeral costs.
Tip:.
Funeral insurance, also referred to as burial insurance or final expense insurance, all share the same significance.
Primary differentiating factors between burial expense policies for seniors and traditional life insurance products include underwriting, coverage levels, and the time it takes to receive payouts.
Firstly, these policies were designed to accommodate individuals with numerous health concerns. The majority of individuals who are in poor health will not meet the requirements for term life insurance or universal life policies. Nevertheless, they will be eligible for a burial insurance policy that does not require a medical examination. Additionally, numerous high-risk conditions can still qualify for a plan without any waiting period.
Moreover, you also have the choice to buy a basic level of insurance. Numerous insurance companies provide coverage starting from as little as $1,000 or $5,000.
Finally, payments are typically distributed within 24-48 hours once claims are authorized.
| Features | Final Expense Insurance | Traditional Life Insurance |
|---|---|---|
| Medical exam required | No | Sometimes |
| Accepting of high-risk medication conditions | Yes | Virtually never |
| Typical minimum coverage amounts | $1,000-$5,000 | $50,000-$100,000 |
| Payout time | Typically 24-48 hours upon claim approval | Can take months to payout |
For a more comprehensive comprehension of the differences between burial insurance and traditional life insurance, please consult the article entitled “burial insurance vs. Life insurance.”
No Exam Vs. No Health Questions
Life insurance policies without exams are different from those without health inquiries.
Life insurance advertisements that solely state “no medical examination required to be eligible” are not assured acceptance.
To clarify the situation:
Considering the widespread occurrence of misleading life insurance advertising, it’s understandable how buyers become confused about these two terms.
Frequently Asked Questions
The sole form of life insurance without a waiting period is a policy that mandates you to respond to health inquiries. While you will need to fill out a health survey, there is no need for you to undergo a medical examination.
All guaranteed acceptance policies mandate a waiting period of at least two years. No company offering a no health question policy provides a waiting period shorter than 24 months.
During the initial two years, in order to receive limited coverage, you are required to respond to health inquiries, similar to obtaining complete immediate coverage. You will need to fill out a health survey and subsequently gain approval from the insurance company, yet there is no need for a medical examination.
Soon after, when people gather large sums of money and purchase a policy while on their deathbed, it shields them from individuals in the waiting period. In order for the insurance company to safeguard the waiting period, they must offer plans without any health inquiries.
To qualify for immediate coverage, there is no requirement for you to undergo a medical examination. However, you will be required to respond to inquiries regarding your health.
Definitely not. In the absence of any health concerns, there will consistently be a waiting period of two years.