What Is Deferred Compensation Life Insurance?
Employers use life insurance as a type of Deferred Compensation to provide benefits to key executives or employees.
This type of insurance policy is designed to provide a death benefit to the beneficiary in the event that the insured employee passes away.
The policy of deferred compensation refers to the aspect of an employee’s compensation that is deferred until a future date, such as retirement.
Throughout that timeframe, the employee acquires the accumulated funds from the plan, which have been growing without any taxation for several years.
Insurance Life Compensation Deferred is often used as a way for organizations to retain and attract top talent. It can also be used as a way for employers to provide additional retirement benefits to their key executives or employees within an organization.
Key Components of Deferred Compensation Life Insurance
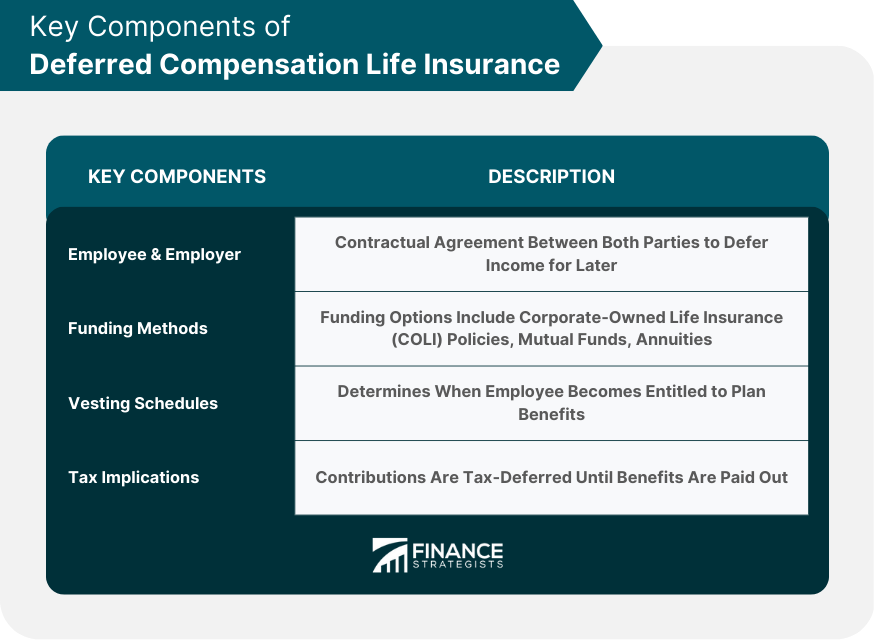
Employee and Employer Agreements
A life insurance plan with deferred compensation is a legally binding agreement between an employee and their employer.
The employer offers particular advantages in exchange for financing the scheme. The worker postpones a fraction of their earnings, which is subsequently invested and disbursed at a later time, typically during their retirement.
Funding Methods
Employers have the option to fund plans with Corporate-Owned Life Insurance (COLI) policies or other investment options, such as mutual funds or annuities. There are various funding methods available for deferred compensation life insurance plans.
Vesting Schedules
An employee becomes eligible for the advantages of a postponed remuneration life insurance scheme when a vesting plan for employees establishes it, taking into account other measures, performance targets, or years of service.
Tax Implications
Generally, contributions to these tax-deferred plans mean that the benefits are not subject to income tax until they are paid out. Both employees and employers have significant tax implications for life insurance compensation deferred under these plans.
Selecting the Right Deferred Compensation Life Insurance Plan
Assessing Company Needs and Objectives
When contemplating a deferred compensation life insurance plan, it is important for employers to take into account various factors such as the preferred level of benefits, employee characteristics, the industry in which they operate, and the size of the company. Employers should conduct a thorough evaluation of their unique requirements and goals.
Evaluating Plan Options
It is important for employers to evaluate different methods of funding and plan options, taking into consideration factors such as regulatory requirements, tax implications, and investment options.
Working With a Financial Professional
These professionals can provide expertise and guidance in managing and selecting the right plan. Employees and employers alike can benefit from working with a professional financial advisor who specializes in life insurance and deferred compensation plans.
Ongoing Plan Management and Review
It is essential to regularly manage and review a deferred compensation and life insurance plan to ensure that the needs of both employees and employers are met, in order to adapt to changes in the environmental regulatory and economic environment.
Risks and Drawbacks of Deferred Compensation Life Insurance
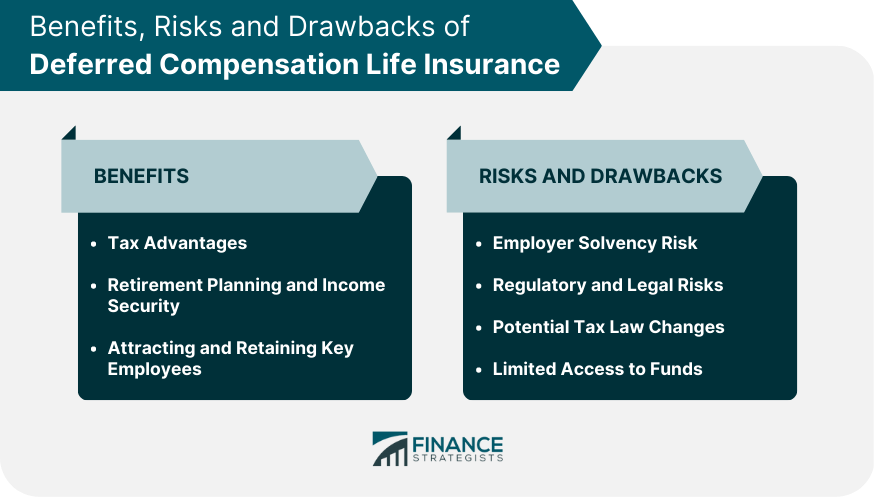
Employer Solvency Risk
Employees may face the possibility of losing the anticipated advantages of the deferred compensation life insurance scheme if their employer is not financially stable at the time of benefit payout.
Regulatory and Legal Risks
Adhering to relevant laws and regulations is crucial to prevent penalties and potential legal action. Employers and employees may encounter regulatory and legal risks tied to deferred compensation life insurance schemes.
Potential Tax Law Changes
Changes in tax laws can potentially reduce benefits for both employers and employees, impacting the advantages of life insurance plans and deferred compensation.
Limited Access to Funds
In case of financial needs or emergencies, an employee’s financial flexibility may be limited by the typically imposed restrictions on accessing funds before retirement in life insurance compensation and deferred compensation plans. Other financial options may be necessary.
Benefits of Deferred Compensation Life Insurance
Tax Advantages
Deferred remuneration life insurance plans provide noteworthy tax benefits for both employers and workers.
Employee Benefits
Employees have the option to defer income tax on their contributions and investment earnings until they receive the benefits, which typically occurs during retirement when they may be in a lower tax bracket.
Employer Benefits
Employers have the ability to subtract their donations to postponed compensation life insurance schemes, offering tax benefits.
Retirement Planning and Income Security
Postponed compensation life insurance plans can aid workers in saving for their later years and offer a source of income throughout their retirement phase.
Attracting and Retaining Key Employees
Offering deferred compensation life insurance plans can help employers attract and retain key employees by providing valuable retirement benefits and financial security.
Estate Planning Advantages
In addition, these plans can offer benefits for estate planning by providing a payout to heirs in case of demise and potentially reducing estate taxes.
Types of Deferred Compensation Life Insurance Plans
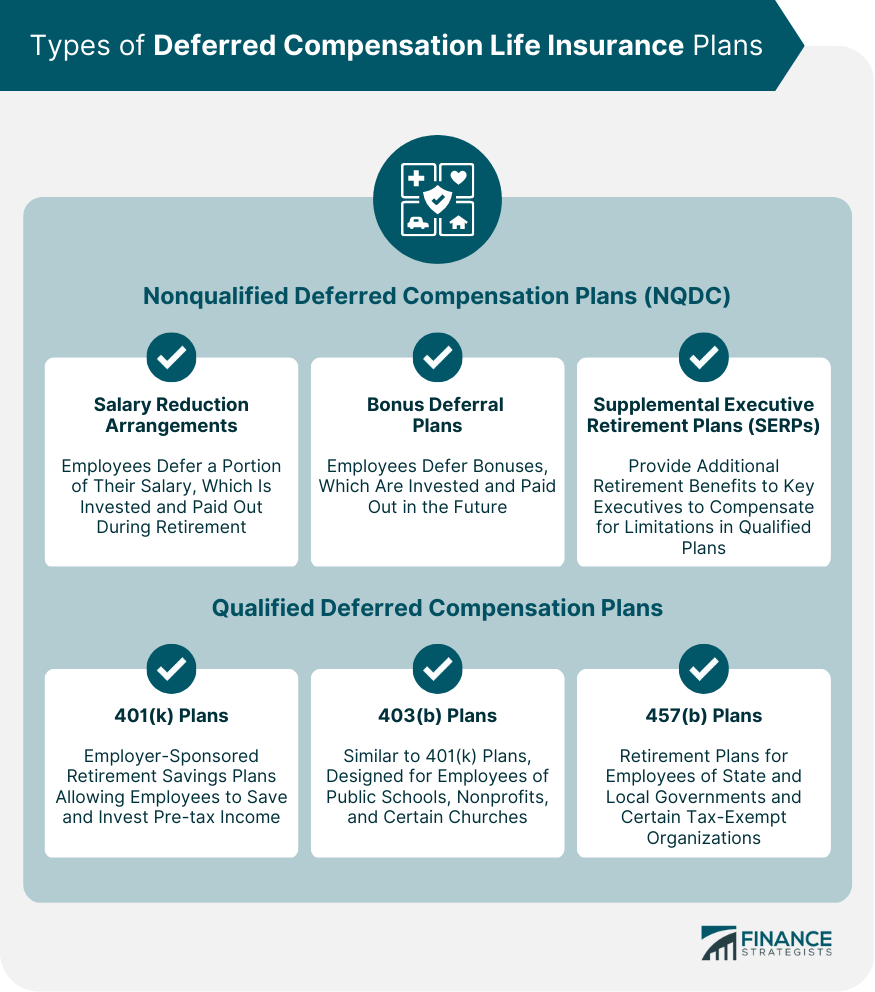
Nonqualified Deferred Compensation Plans (NQDC)
Providing more flexibility for both employers and employees, examples of NQDC plans include nonqualified deferred compensation plans that are not subject to the same regulations as qualified plans.
Salary Reduction Arrangements
Typically, employees defer a portion of their salary during retirement, which is subsequently invested and disbursed at a later time.
Bonus Deferral Plans
These plans enable employees to postpone bonuses, which are subsequently invested and distributed at a later time.
Supplemental Executive Retirement Plans (SERPs)
Search Engine Results Pages (SERPs) are designed to provide additional retirement benefits to key executives, often in order to make up for limitations in eligible programs.
Qualified Deferred Compensation Plans
These plans are subject to strict regulations under the Employee Retirement Income Security Act (ERISA). Examples of qualified deferred compensation plans include:.
401(k) Plans
The deduction of taxes occurs prior to employees setting aside a portion of their salary for savings and investments, enabling employers to support a retirement savings scheme known as a 401(k).
403(b) Plans
Like 401(k) plans, 403(b) plans are specifically created for public school employees, non-profit organizations, and specific churches.
457(b) Plans
457(b) plans are specifically created for workers employed by state and local governments, as well as specific tax-exempt organizations.
The Bottom Line
Deferred remuneration life insurance plans function as valuable financial planning instruments for both employers and employees.
These strategies provide significant benefits, such as tax advantages, planning for retirement, maintaining financial stability, and the capability to attract and retain essential personnel.
Features and regulations unique its with each, plans compensation deferred qualified and plans compensation deferred nonqualified: of types main two are there.
However, it is crucial to consider the potential drawbacks and risks associated with limited access to retirement funds and changes in tax laws, as well as the legal and regulatory risks and the solvency risks for employers.
Employers should assess their company’s specific objectives and needs by working with a specialized professional in financial planning, evaluating various funding methods and plan options, including deferred compensation and life insurance.
It is essential for both employees and employers to meet the needs of the chosen plan by ensuring regular management and review, in order to adapt to changes in the regulatory and economic environment.