Disability Insurance for Lawyers: What You Need to Know
One of the most prevalent dangers in a legal profession is experiencing a long-lasting or irreversible handicap. Although various factors can obstruct a legal career, the value of being able to practice law diminishes if your education costs exceed $300,000 but cannot be translated into substantial financial gains through years of working in the legal sector. The primary financial jeopardy for attorneys lies in the loss of the capability to translate the extensive education acquired over almost ten years into a significant accumulation of wealth by practicing law for several decades.
Every year, numerous attorneys are rendered unable to work, and the primary reason for this disability is either physical or mental illness. As per insurance providers, the leading factors behind disability insurance claims consist of pregnancy (6.8%), mental health disorders (9.3%), injuries (12%), cancer (15%), and problems related to the musculoskeletal system and connective tissues (27.6%). Often, individuals envision such disabilities arising from a sudden and dramatic accident.
In this article, I will assist you in comprehending the coverage you possess, including the process of purchasing it and determining if additional protection is required. It appears that many colleagues are unaware of the advantageous provision offered by law firms, namely the inclusion of group disability insurance coverage.
Biglaw Associate Group Disability Coverage
Find a policy for you
Our website is filled with content that can help you learn everything you need to know about buying disability insurance policies. If something goes wrong, and you need to make a claim, it’s important to have a policy that protects your income. But, you also know intuitively that your continued health is key to your wealth. Lawyers see risk everywhere, as it is a part of their profession.
Please consider giving us a chance. When you are prepared to assess quotations, we diligently search the providers on your behalf to discover the most affordable prices accessible and the best overall offer.
Compare Quotes.
Patrick Waldrop was incredibly helpful and knowledgeable, always pushing himself to assist me. He did a fantastic job with the insurance disability and life insurance policies I obtained from Audho Pradeep.
Pradeep, who is incredibly knowledgeable, has helped me understand the nuances and coverages of the product. He has walked me through several disability policy scenarios, which continues to be valuable resources for my wife and me. I have questions when it comes to trusting my earned resources, and he is important to me.
How to get even deeper discounts
One of the reasons we, as an independent insurance agency, want companies to know that we compete for disability insurance business is because of Sidebar, which we have set up.
We’re excited to say that if you bring two colleagues from your firm who buy a supplemental policy at the same time, we can offer an additional 20-45% off on insurance policies for companies.
Not just that, but the insurance company will also persist in providing that discount to all individuals at your organization in the future. By taking the lead for your firm, you will not only assist present and future associates, but you will also benefit from the ongoing support.
How can we obtain this discount of 20-45%? There are two factors that contribute to this: group vulnerability and
Insurance companies will provide discounts to attorneys employed at the identical firm (which refers to the “group risk”).
Another reason is that the insurance company will provide a policy that is suitable for both genders.
This advantage is particularly great for female attorneys.
Therefore, when offering sex-specific insurance policies, a company will charge men a higher price than women for the same policy. This is because insurance disability is based on actuarial risk tables, which results in women paying less for term life insurance but significantly more for disability insurance.
If we are able to get three people from a firm, we can convince the insurance company to write a unisex policy for disability supplemental insurance, regardless of whether they are women or men.
A gender-neutral policy is exactly as it sounds. The policy is priced the same irrespective of gender.
The unisex policy will be considerably more affordable for women. Meanwhile, men will also generally discover that unisex policies are less expensive due to the accompanying group discount.
If you wanted to cover 70% of your income, here’s how much supplemental coverage you need.
Obtain quotations for additional disability insurance coverage.
| Class | Salary | Bonus | Total Compensation | Group Disability Monthly Benefit (Taxable) | Supplemental Monthly Benefit (Tax-Free) | Total Compensation Replaced |
|---|---|---|---|---|---|---|
| 1st Year | $215,000 | $20,000 | $235,000 | $10,750 | $2,219 | 70.0% |
| 2nd Year | $225,000 | $30,000 | $255,000 | $11,250 | $2,719 | 70.0% |
| 3rd Year | $250,000 | $57,500 | $307,500 | $12,500 | $4,078 | 70.0% |
| 4th Year | $295,000 | $75,000 | $370,000 | $14,750 | $5,125 | 70.0% |
| 5th Year | $345,000 | $90,000 | $435,000 | $15,000 | $7,781 | 70.0% |
| 6th Year | $370,000 | $105,000 | $475,000 | $15,000 | $9,531 | 70.0% |
| 7th Year | $400,000 | $115,000 | $515,000 | $15,000 | $11,281 | 70.0% |
| 8th Year | $415,000 | $115,000 | $530,000 | $15,000 | $11,938 | 70.0% |
Modify the figures accordingly, it is necessary to possess a policy with a higher or lower advantage in case you possess a conventional group disability insurance policy with a monthly benefit limit of $15,000 or 60% of your basic salary, whichever is smaller. This chart supposes that.
My supplemental policy details and cost
If I were to become disabled and experience a severe decline in my lifestyle, I would suffer greatly and be at too much risk. The coverage offered by the senior associate at the firm represents this high risk. Additionally, the policies available for purchase are not expensive and make it easier for me to make a decision.
My supplemental disability insurance policy includes a variety of riders, such as an enhanced catastrophic disability rider and an enhanced partial disability rider. It also offers the option to increase rider benefits in the future. It is important to remember that this benefit is tax-free, and the policy pays a monthly benefit of $6,000.
The total expense amounts to approximately $2,300 per year or roughly $190 per month. For a senior associate earning $415,000, this insignificant sum allows me to mitigate risk and undoubtedly improves my sleep at night.
In order to obtain quotations, the subsequent measure entails conversing with an autonomous insurance broker who can procure quotations from all of them. Merely a few providers vend personal incapacity insurance, thus if you have a desire to procure an additional policy, it would be wise to acquire quotations.
Policy insurance disability supplemental a for quote customized a you get help can–lawyers by created one only the Sidebar company insurance our.
Our approach is quite straightforward: discover the most affordable plan with the protection you genuinely require.
If we are aware of a more advantageous discount that is accessible elsewhere (e.G. Through bar associations), we will not hesitate to direct you towards it, even if it means that we do not receive any compensation. Moreover, we will endeavor to apply the most favorable policy available and conduct a thorough search for it if you obtain a quote through our services.
We have partnered with fellow agents Matt and Pradeep, who have more than a decade of experience in writing own-occupation policies, to provide guidance and policy options to other high-income professionals and lawyers. In fact, I bought my policy through Pradeep.
A look at how much income protection a Biglaw associate has with a group policy that has a $15,000 or 60% cap.
Obtain quotations for additional disability insurance coverage.
| Class | Salary | Bonus | Total Compensation | Group Disability Monthly Benefit (Taxable) | Supplemental Monthly Benefit (Tax-Free) | Total Compensation Replaced |
|---|---|---|---|---|---|---|
| 1st Year | $215,000 | $20,000 | $235,000 | $10,750 | $0 | 54.9% |
| 2nd Year | $225,000 | $30,000 | $255,000 | $11,250 | $0 | 52.9% |
| 3rd Year | $250,000 | $57,500 | $307,500 | $12,500 | $0 | 48.8% |
| 4th Year | $295,000 | $75,000 | $370,000 | $14,750 | $0 | 47.8% |
| 5th Year | $345,000 | $90,000 | $435,000 | $15,000 | $0 | 41.4% |
| 6th Year | $370,000 | $105,000 | $475,000 | $15,000 | $0 | 37.9% |
| 7th Year | $400,000 | $115,000 | $515,000 | $15,000 | $0 | 35.0% |
| 8th Year | $415,000 | $115,000 | $530,000 | $15,000 | $0 | 34.0% |
Modify the figures accordingly, it is necessary to possess a policy with a higher or lower advantage in case you possess a conventional group disability insurance policy with a monthly benefit limit of $15,000 or 60% of your basic salary, whichever is smaller. This chart supposes that.
If you are worried about the group policy’s coverage, it may be beneficial for you to consider obtaining a supplemental policy in case of disability.
Given by the company, you still have the opportunity to utilize the advantage since it is pleasant that you don’t need to go out and purchase a complete policy. Your supplementary policy will be exactly that: supplementary, therefore disability insurance providers generally only permit you to purchase coverage for approximately 60-70% of your earnings and take into account your entire disability insurance coverage. The initial step you’ll need to take is determining the amount of extra coverage you require.
The post-tax policy will provide you with a tax-free benefit, so keep in mind that you will need to pay for the supplemental policy. The Monthly Supplemental Benefit column shows the amount you would need to cover your policy, which is set at 70% of your income. The difference is the same basic information contained in the chart below.
Besides increasing your coverage, here is a list of typical reasons why individuals buy additional insurance:
Supplemental Disability Coverage
Is my firm’s plan good enough?
The most crucial aspect to consider about disability insurance is that having any form of disability insurance is more advantageous than having none. For instance, group disability insurance policies offered by reputable companies like Unum are preferred by the majority of Vault 100 firms.
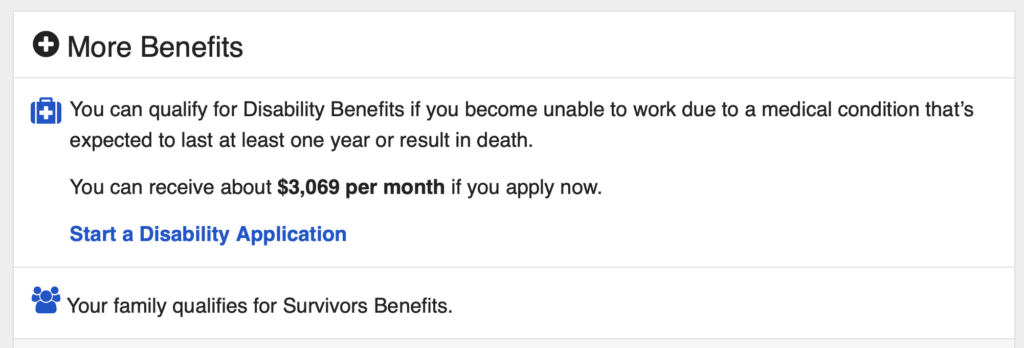
Surviving on $3,000 per month would entail a significant reduction in our quality of life. According to my most recent Social Security statement, my monthly disability benefit would amount to $3,069. If one were to become disabled without disability insurance, they would be constrained to rely on the payouts offered by the Social Security Administration, which tend to be relatively meager and challenging to secure.
Since the firm provides pre-tax benefits, you can benefit from any payout from your taxable dollars. In this industry, it could be possible for the total compensation of yours to be delivered in the form of bonuses. It is important to note that most disability insurance policies do not cover special bonuses or annual bonuses. Therefore, it is crucial to understand that the previous sentence does not apply to your base salary when it comes to disability insurance policies.
The chart below contains some familiar numbers from the Biglaw Salary Scale, specifically the two columns: Compensation and Monthly Benefit. Pay attention to the particular base salary of your group, assuming you have a disability insurance policy with a monthly cap of 60% or $15,000, whichever is lesser. It also includes the calculation of your group’s disability insurance coverage.
The amount you would receive is the Group Disability Monthly Benefit column if you become disabled. Once you pay taxes, could you afford to live on the monthly benefit? Would it cover basic living costs like rent/mortgage, food/groceries, and utilities? Nearly all disability insurance policies stop paying when you reach age 65, so you also need to be able to save for retirement with this monthly benefit. And, don’t forget that you’re disabled in this scenario, so could you afford to pay for extra help around the house if needed?
The Total Compensation Replaced column provides an understanding of the amount of income that would be substituted if you were to become disabled. As you can observe, it is approximately 60% for a 1st year associate but decreases rapidly as you progress in the hierarchy. A mid-level associate would receive replacement income around the mid-40%, while a senior associate would only anticipate coverage of around 30%.
Speciality specific disability insurance policies
If you’re seeking additional information regarding particular areas of expertise, take a look at these articles:
Doctors.
Dentists.
Self-Employed.
Entrepreneurs who
Surgeons.
Prior to joining Biglaw Investor, Josh worked as a lawyer specializing in private equity mergers and acquisitions at one of the country’s largest law firms. He has extensive expertise in the field of insurance, specifically in the areas of life and disability insurance, with a focus on providing coverage for lawyers, doctors, and other high-income professionals. Joshua Holt is a licensed insurance agent (License #2785989) and the founder of Insurance Sidebar and Investor Biglaw, an insurance agency established by lawyers for lawyers.
I simply trust my hardworking friend. When it comes to my wife, I have some important questions and he continues to provide valuable resources. Pradeep has helped me understand the details and coverage of the product, and he has guided me through various disability policy situations. He is extremely knowledgeable.