Explore further about our areas of expertise or request a quotation today.
Learn About Universal Insurance Agency, Inc.
Universal Insurance Agency, Inc. Prioritizes customer contentment, and our operational approach is centered on that. In contrast to renowned insurance providers, we act as a representative because we are an autonomous insurance agency. Your requirements are attentively addressed by knowledgeable, proficient consultants who possess market expertise and provide guidance. The process of obtaining and assessing insurance policies may be intricate and overwhelming, but we offer assistance.
Give us a call today to begin. With our company, you receive excellent service and great value for your investment that is difficult to refuse. We work with more than 70 insurance providers in order to offer you a wide range of coverage choices and affordable rates. We are honored to assist residents in Worcester, MA, Milford, MA, and throughout the entire state of Massachusetts.
Discover More About Us
Friendly insurance, conveniently available at your doorstep. Call or visit today.
We take pride in serving our local communities in both Milford and Worcester, Massachusetts, with the highest quality customer care and service.

Esteemed Individuals of Renaissance Alliance.
We are committed to bringing the highest quality services and products to our customers, through our carefully selected group of independent agents, with membership in the Renaissance Alliance.
Learn More.
Seeking for answers? We possess what you require.
The Universal Benefit.
What sets our autonomous insurance agency apart?
We provide a diverse range of insurance options.
We are here to support you during your moments of necessity.
We are with you throughout the entire journey.
We are authorized insurance consultants.
Additional airlines. Increased options.
We work with over 70 insurance companies to provide a wide range
Fire.
Risk Factor……………
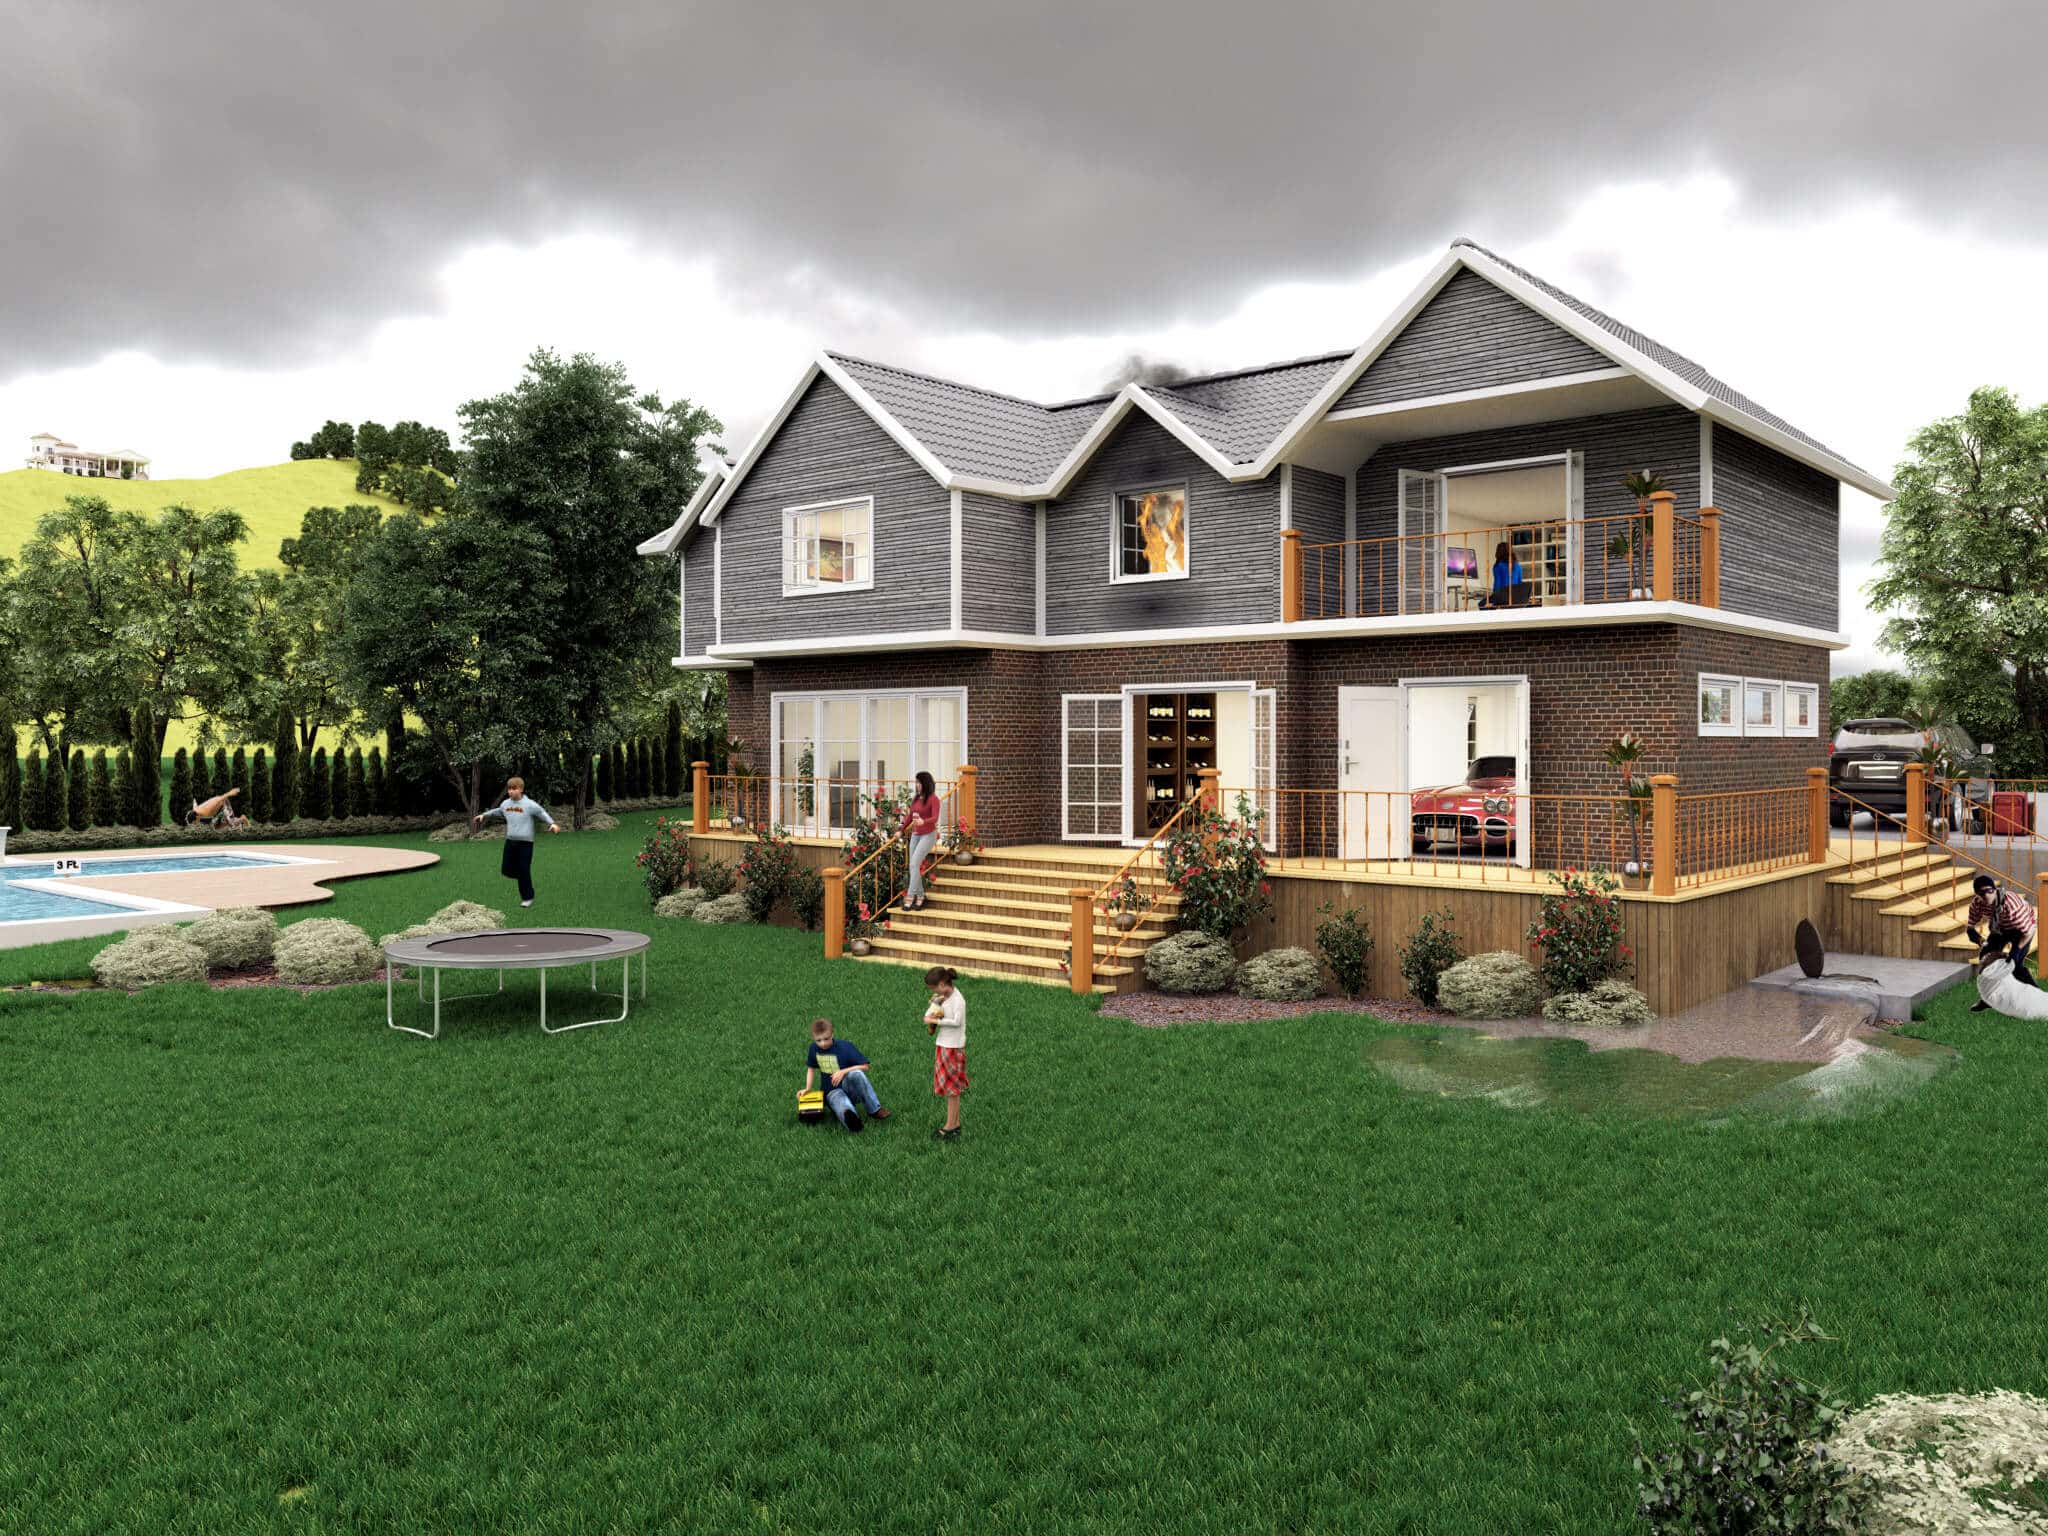
Rebuilding a home can often cost significantly more than the actual construction and material expenses due to inflation rates. It is important to remember to have adequate insurance coverage to replace the contents of your home in case of fire. Fires can have a significant impact on your home, causing both physical and emotional damage, and they are often devastating.
Solution……………
It is important to ensure that your homeowners policy includes coverage for replacement cost without any limitation. Make sure that the coverage limit of your current policy is higher than the cost of rebuilding your home, taking into account any additional expenses that may be required due to changes in local building codes and ordinances, which can often be quite significant.
Personal Belongings / Possessions – Damage to Property.
Risk Factor……………
When your home suffers damage due to an unexpected event, other personal items and electronics, clothing, appliances, and furniture are also at risk of being damaged or destroyed.
Solution……………
Make sure your homeowners insurance policy includes the cost of full replacement coverage for damaged items, so that you always receive the full cost when you need to replace whatever item. Typically, homeowners insurance policies cover personal property, including the contents of your home and other personal items owned by you or your family members who live with you.
Additional Living Cost / Loss of Utilization.
Risk Factor……………
When unexpected events like lightning, fire, or a storm cause substantial damage to your home, it may not be habitable, requiring you to find alternative accommodations and incur additional living expenses for lodging, food, and other daily necessities. Furthermore, you might also need to consider repairing or rebuilding your home.
Solution……………
Ensure that your homeowners insurance policy provides coverage for additional living expenses and temporary housing costs if your house becomes uninhabitable and needs to be rebuilt or repaired, so you can be compensated for the reasonable costs you incur for living and housing during the event.
Valuable Possessions.
Risk Factor……………
Usually, homeowner insurance policies have a maximum limit for valuable items like jewelry, fur, artwork, and other collectibles.
Solution……………
Obtain a personal flotation device or make arrangements for safeguarding your valuable possessions to guarantee that you will have the resources to replace them.
Medical Expenses.
Risk Factor……………
You may be obligated to cover any healthcare costs related to their injury if a visitor gets hurt on your premises, even in the event of an accident during a casual baseball match.
Solution……………
You are typically not paid for medical expenses filed against a liability claim without a claim being submitted to your insurance carrier. You should be able to submit your medical expenses to your insurance carrier for attention, as long as the person injured on your property is not seriously injured. Your homeowners policy should include coverage for medical expenses, including treatment and care for injuries.
Personal Liability.
Risk Factor……………
If someone unfortunately experiences any injuries that lead to slips and falls while on your property, you and your family may be held responsible.
Solution……………
It is important to consider purchasing a personal umbrella or excess liability policy to provide additional coverage limits in case a lawsuit is brought against you. This will help protect your assets, as your homeowners policy includes personal liability coverage to respond to incidents where injuries or damages occur to a third party and you may be deemed negligent.
Miscellaneous Coverage.
Risk Factor……………
The coverage provided by insurance companies for homeowners’ policies may vary from state to state, and it may not include the serious risks associated with having a trampoline in your backyard, which can also bring fun.
Solution……………
You should make sure that your homeowners insurance policy covers the trampoline, as many insurance providers refuse to take liability and exclude coverage for this item.
Personal Harm / Slander.
Risk Factor……………
Young people are typically very active online; therefore, there is a possibility that their increase in using social media and other websites can indirectly or directly expose their parents to a lawsuit and damage someone’s reputation.
Solution……………
You may need to seek additional coverage to include personal injury or defamation protection that covers liability. Your homeowners insurance policy includes liability coverage for property damage caused by any member in the family, but it is unlikely to cover reputation damage caused by statements or rumors.
Umbrella / Additional Liability Coverage.
Risk Factor……………
Do you have enough money saved to cover your legal defense costs as well as your legal responsibilities? After your family is left financially responsible for their injuries, they hire a lawyer to represent them in a long legal battle. One of your invited guests dives into the shallow end of your pool and becomes permanently injured.
Solution……………
Excess liability insurance is offered to homeowners through an endorsement, allowing for separate coverage if desired. By adding an umbrella policy or increasing the limits of your current homeowners, boat, or auto insurance, you can enhance the financial security and value provided by your policies, thereby increasing your personal liability limits.
Flood Coverage.
Risk Factor……………
If you live near a body of water, you do not have to suffer loss due to flooding. The changing weather patterns and increasingly damaging storms around the globe are causing more frequent and common losses from floods in places that are not normally prone to flood damage. Unfortunately, your homeowners policy does not cover damage from floods.
Solution……………
Purchase a flood insurance policy from the National Flood Insurance Program (NFIP) to protect your home and its contents from certain types of flood losses.
Secondary Home.
Risk Factor……………
Possessing a second residence has the potential to amplify your liability risks.
Solution……………
Add your secondary residence to an excess liability or umbrella policy to ensure extra coverage for liability limits. Additionally, contemplate expanding the liability protection of your homeowners policy to encompass your secondary home.
Collector Cars.
Risk Factor……………
Classic vehicles or collector cars, which often have significant value, are typically not covered under your homeowners insurance, even if stored on your property. To ensure that they are adequately protected, unique insurance coverage and special documentation are required.
Solution……………
Insure your collector cars with a specialized insurance company that understands and focuses on unique vehicles, including classic cars and other collector cars.
Wine Collection.
Risk Factor……………
If your homeowners policy covers a loss caused by insurable damage, it is possible to seek recourse. However, if you are a wine connoisseur, it is important to note that your collection may be susceptible to damage from environmental exposures that are not covered by your homeowners policy.
Solution……………
If you have a sizable collection of wine, you may want to consider scheduling the wine collection on your homeowners policy. Doing so eliminates the deductible in case of loss and expands your coverage. Additionally, wine spoilage is also covered uniquely.
Water Damage.
Risk Factor……………
Whether it is caused by a flood or by issues within your home’s plumbing system, water damage is the primary reason for loss in a home. Numerous policies do not cover losses resulting from the backup of sewers and drains, and all homeowner policies without endorsements exclude damage caused by floods.
Solution……………
Firstly, ascertain cost-effective measures to tackle the potential harm caused by floods. This includes considering insurance coverage options provided by companies that suggest a thorough assessment to safeguard your residence and personal possessions against any form of water-related destruction, such as sewer and drain backups.
Off-Premises Theft.
Risk Factor……………
Interestingly, regular car insurance does not provide coverage for personal belongings or items stolen from your vehicle.
Solution……………
Most homeowners insurance policies provide the choice to add off-site theft coverage as an endorsement, which safeguards you against the theft of your belongings outside of your home.
Discover Additional Information Regarding This Insurance Coverage
Click it. Read it. Conceal it.
Not what you’re seeking?
Discover a wider range of engaging
Control Your Policies.
Already a customer of Universal Insurance Agency, Inc.? Stop by our Service Center to submit requests and handle your insurance.
Visit the Service Center
We Enjoy Receiving Feedback from Our Satisfied Customers.
Take a look at our evaluations and discover why you should make the switch to Universal Insurance Agency, Inc.
Check out our Google Reviews.
For about 15 years, I have been utilizing Universal Insurance for both my auto and business insurance. I can confidently say that they are the absolute best and I have no doubt in their services.
Ana M.
I had my auto insurance with Universal Insurance for many years. The customer service above all was great. The highly trained professional staff was always able to assist me when I needed help.
Sam S.
“I highly recommend it! She was very patient with me and made it extremely simple and easy. Jackie was the best and this is my first time looking for insurance.”
Hayley S.
For all your insurance needs. Output: Get
“*” Denotes necessary fields.