Learn About Reed Insurance Agency
Are you in need of insurance? We are independent agents committed to customizing coverage insurance to fit your needs, budget, and risks. We are here to help you prepare for accidents that may occur and ensure that you are financially protected from the aftermath of unexpected events. Finding an insurance plan can be challenging in today’s market.
Contact us and discover the extent of our capabilities! Our affordable prices, the knowledgeable representatives who take the time to understand your unique needs, and the excellence of the merchandise we provide are the means by which we achieve this. We aspire to be your primary and reliable option in safeguarding your interests, and we have the support of over 96 years of industry expertise and 23 years of being recognized as Mid-Michigan’s esteemed insurance agency since 1926.

For 23 years, Reed Insurance Agency has been honored with the People’s Choice Award as the preferred Insurance Agency in Mid Michigan.
The Answer to Your Insurance Requirements.
If you are located in Ohio, Indiana, or Florida, we are pleased to offer you the same service coverage as your hometown. Feel free to visit our local office in DeWitt, MI or give us a call.
Contact Us.
Delighted to Be Your Preferred Option.
High-quality coverage. Customized service. Rates that bring you joy.
The Benefit of an Independent Agency
What sets our autonomous insurance agency apart?
We provide a diverse range of insurance options.
We are available to support you during your period of necessity.
We are with you throughout every stage of the journey.
We are authorized insurance consultants.
A Self-governing Organization Provides You Choices.
We proudly showcase Hanover Insurance, Grange, and additional providers
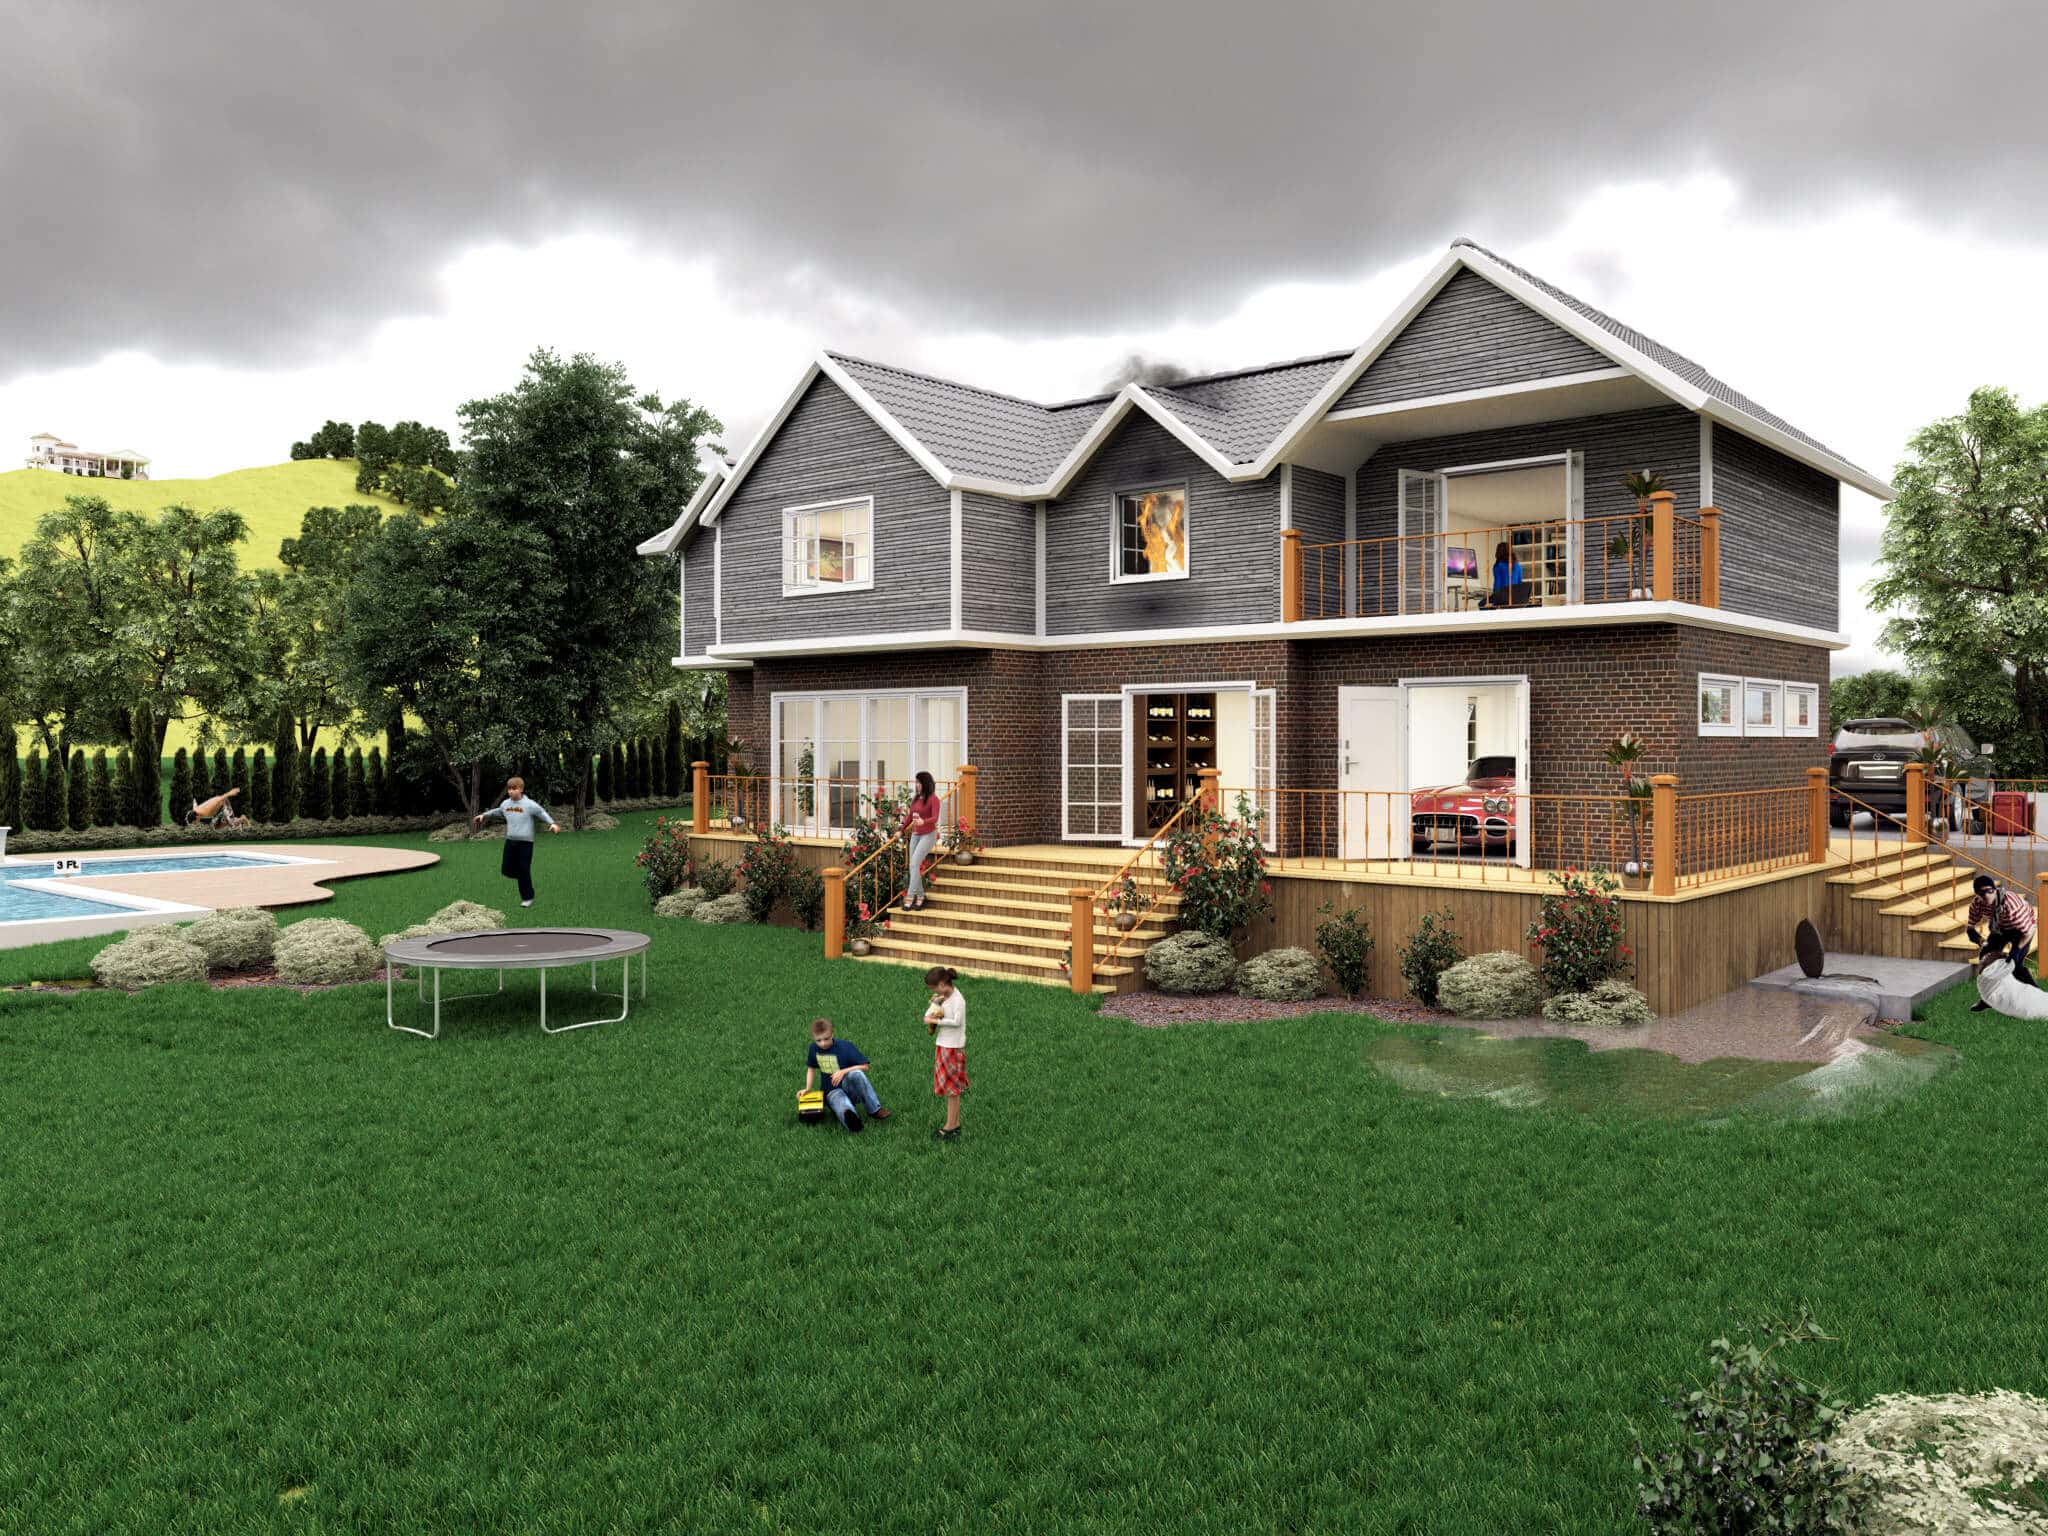
Fire.
Risk Factor……………
Home rebuilding results can often incur costs significantly higher than anticipated. It is important to note that real estate values rarely align with construction and material costs due to inflation rates. Therefore, it is crucial to ensure that you have adequate insurance coverage to replace the contents of your home in case of fire. Besides the physical damage, fires can also have a significant emotional impact. Most fires are devastating.
Solution……………
The homeowners policy you have ensures that there is no limit on coverage with replacement cost. If the cost to reconstruct your home is higher than your current limit, this coverage protects you. Additionally, it is important to make sure that your insurance includes code to rebuild your home. Building codes and local ordinances often change over time, which may require additional costs.
Personal Belongings / Possessions – Property Destruction.
Risk Factor……………
Your personal belongings, such as furniture, appliances, clothing, electronics, and other items, may also be at risk of being damaged or destroyed when your home experiences unexpected damage.
Solution……………
Make sure your homeowners insurance policy includes replacement cost coverage for personal property, including the contents of your home and other personal items owned by you or your family members who live with you, so that you always receive the full cost of replacing whatever damaged item.
Additional Living Costs / Loss of Utilization.
Risk Factor……………
You might have to face extra living costs for accommodation, meals, and other everyday necessities while your house is being fixed or reconstructed, possibly as a result of unforeseen circumstances like a lightning strike, fire, or severe weather conditions, which can cause significant harm to your residence.
Solution……………
Ensure that your homeowners insurance policy provides coverage for additional living expenses or additional costs incurred for reasonable housing if your temporarily uninhabitable house needs to be rebuilt or repaired, in the event that you incur expenses for living and housing while your event is covered.
Valuable Possessions.
Risk Factor……………
Usually, homeowner insurance policies have a limit on valuable belongings, such as jewelry, fur, fine arts, and other collectibles.
Solution……………
Acquire a personal buoy or plan the protection of your valuable belongings to ensure you will have the funds to replace them.
Medical Expenses.
Risk Factor……………
Associated with their injury, you may be obligated to cover all medical costs, even if it arises from a casual match of baseball, in the event that a visitor sustains an injury while on your premises.
Solution……………
Typically, medical expenses incurred due to injuries and treatment are usually not covered by your homeowner’s insurance policy. However, in the event that a person is injured on your property and requires medical attention, you may be able to submit these injury-related medical expenses to your insurance carrier for reimbursement.
Personal Liability.
Risk Factor……………
In the unfortunate circumstance that someone experiences any injuries, you and your family may be held responsible for slips and falls on your property.
Solution……………
If injuries or damages happen to a third party, leading to accusations of negligence, your homeowners policy should cover personal liability. In case a lawsuit is filed against you to safeguard your assets, it is advisable to acquire a personal umbrella or excess liability policy for extra coverage limits.
Miscellaneous Coverage.
Risk Factor……………
Having a trampoline in your backyard can come with fun but may not be covered under the standard homeowners insurance policy, as it can also be accompanied by serious risks. Insurance coverage for trampolines varies between companies and from state to state.
Solution……………
Many insurance providers refuse to cover liability and exclude trampolines from their insurance policies, so you should make sure that your homeowners insurance policy covers your trampoline.
Personal Harm / Slander.
Risk Factor……………
Engaging in a lawsuit as a parent, and potentially causing harm to someone’s reputation, can be heightened by the use of social media and other popular online platforms, particularly among young individuals.
Solution……………
You may need to seek additional coverage to include protection for personal injury or defamation. Your homeowners insurance policy includes liability coverage for property damage caused by any member of the family, but it is unlikely to cover reputation damage caused by statements or rumors.
Umbrella / Additional Liability Coverage.
Risk Factor……………
Do you have enough money saved to cover the legal costs and responsibilities as well as defend yourself? Your family and you are financially responsible for their injuries, and after a long legal battle, they decide to hire a lawyer to represent them. One of your guests dives into the shallow end of your pool and is permanently injured, so you invite them and other guests over for a pool party.
Solution……………
An umbrella or excess liability policy enhances your personal liability limits by offering additional protection above and beyond your existing auto, boat, or homeowners policies, thereby providing both financial value and security. Excess liability insurance can be obtained as a separate coverage, either through an endorsement to your homeowners policy or through other means.
Flood Coverage.
Risk Factor……………
Living near a body of water does not expose you to the risk of flood damage. Unfortunately, your homeowners policy does not provide coverage for flood damage. However, it is important to note that with the changing weather patterns and increasing occurrence of damaging storms around the globe, even places that are not typically prone to flooding are experiencing more common losses.
Solution……………
Purchase a separate flood insurance policy through the Federal Flood Insurance Program (NFIP) to serve as your own carrier. This policy, designated by the National Flood Insurance Program, covers certain types of flood losses to protect both your home and its contents.
Secondary Home.
Risk Factor……………
Possessing a second residence has the potential to enhance your liability risks.
Solution……………
Add your second residence to an additional liability or umbrella policy to ensure extra coverage for liability limits. Moreover, expand the liability protection of your homeowners policy to encompass your secondary home.
Collector Cars.
Risk Factor……………
Classic or collector vehicles often require unique insurance coverage and documentation, as they are typically not adequately covered under homeowners insurance, even if they are stored on your property.
Solution……………
Insure your collector cars with a specialized insurance company that understands and focuses on unique vehicles, including other types of vehicles such as classic cars.
Wine Collection.
Risk Factor……………
A deductible may also be applicable. Your home insurance policy specifies the covered perils, making the harm insurable. If the collection is damaged, coverage from your home insurance policy can be a potential remedy. As a wine enthusiast, you are aware that wine is vulnerable to external environmental factors that can spoil it.
Solution……………
To prevent damage, you can also explore distinctive protections for wine. By doing this, you broaden your coverage and remove the deductible in the event of a loss. If you possess a substantial wine collection, it might be worth contemplating adding the collection to your homeowners policy.
Water Damage.
Risk Factor……………
The most common cause of loss for many homeowners is water damage, which can occur from a flood or from water entering your home’s plumbing system or from outside. This type of damage is not covered by homeowner insurance policies, which exclude losses caused by floods and damage to drains and sewers that result from the backup.
Solution……………
Essential for protecting your home and belongings from all forms of water damage is a careful review. We suggest insurance company coverage solutions that encompass the backup of sewers and drains. Additionally, it is important to identify cost-effective measures to mitigate the risk of flood damage initially.
Off-Premises Theft.
Risk Factor……………
Interestingly, typical automobile insurance does not provide coverage for personal belongings or items stolen from your vehicle.
Solution……………
Most homeowners insurance policies offer an option to include coverage for theft off-premises, which covers theft of your personal property away from your residence, as an endorsement.
Discover Further Details About This Insurance Coverage
Click on it. Read it. Conceal it
Not the desired outcome?
Discover a wider range of engaging
Control Your Policies.
Are you already a customer of Reed Insurance Agency? Stop by our Service Center to submit requests and oversee your insurance.
Get in touch with Reed Insurance
“*” Denotes mandatory fields.