Save funds by comparing insurance estimates from various providers.
What type of job do you perform?
We collaborate with reputable insurance companies that have an A-rating.
Surety bonds
If the services contracted by the client fail to be delivered, the insurance company, acting as a surety bond between a business and a client, will guarantee to reimburse the business.
What do surety bonds not cover?
While a surety bond protects your business from financial loss caused by clients, it does not protect your business against its own losses or damages. In fact, your business is responsible for paying back any amount paid to a client through the bond.
This is why it is essential to possess insurance for small businesses. For instance, a surety bond does not offer protection for: .
Damaged client property
Look to your general liability insurance policy for financial protection against accidental property damage for your client. However, make sure to also provide property damage coverage for the client’s theft through a surety bond.
Accidental injuries
In your workplace, if a customer slips and experiences harm, like unintended harm, general liability insurance also offers monetary security. To meet the requirements of a lease, loan, or agreement, this policy may be necessary.
Breach of contract
Data breaches
Discover quotations for insurance coverage for small businesses and surety bonds.
What do surety bonds cover?
They also help small businesses obtain the necessary permits and licenses in the event that your business fails to fulfill the terms of a contract or complete a project, ensuring that your client will receive financial reimbursement through a surety bond.
Specifically, surety bonds frequently offer protection for:.
Failure to complete a project
If a commercial builder takes on a large construction project, they may not be able to finish it by the agreed upon deadline due to some supply chain issues causing delays in the delivery of certain parts.
Failure to comply with standards or regulations
If an inspection reveals wiring installed by a non-electrician in a home, the property owner can reimburse the cost of hiring another contractor to do the rewiring through a surety bond.
License and permit requirements
Employee theft
A fidelity bond can reimburse the client for the stolen amount if an employee at a financial planning firm conducts an illegal electronic funds transfer to their own account, for example. Clients are reimbursed for employee theft by a type of surety bond known as a fidelity bond.
Who needs a surety bond?
Depending on the sector you operate in and the nature of your job, you might require a surety bond in order to submit a bid for a project, acquire a license, or obtain a work permit. Various forms of bonds are available to cater to the distinct risks faced by professionals in a wide range of industries, and these surety bonds serve to safeguard them.
Here are a few instances of the foremost occupations that depend on surety bonds or are obligated to possess them.
Construction businesses
The specific value of the bond is determined by either state legislation or the client, and in certain areas, a bond is required for general contractors to acquire a license. Construction companies and contractors typically require both construction bonds and insurance.
The building sector has various forms of guarantee bonds, including:
Professional services
Business owners who provide professional services often need to obtain a bond in order to comply with state requirements for their profession or to sign a contract with a client, for example, bonds that are required by laws usually aim to protect the public from potential errors made by a public notary.
Wholesalers
Wholesalers may also necessitate surety bonds, generally to offer peace of mind to customers that they will deliver products as mutually agreed upon in a contract.
Insurance professionals
Auto services
Surety bonds are frequently required by state law for both new and used car dealerships. An auto dealer bond, provided by the dealer, safeguards the public from any misrepresentation or fraud committed by the dealer.
Cleaning businesses
The insurance company will reimburse the client for the bond amount if any of your employees engage in theft of jewelry or cash from a client, which are referred to as janitorial bonds in this scenario. Clients frequently demand cleaning companies to possess bonds.
You might also enjoy.
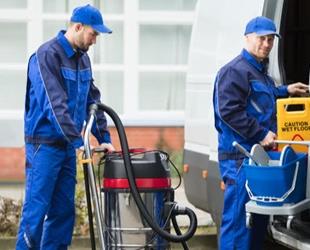
What you should be aware of regarding licenses and bonds for cleaning businesses.
Operating within the legal framework is essential when it comes to obtaining insurance for your commercial and bonding needs. In order to conduct your cleaning business, you may require licenses. By ensuring that you have these additional forms of protection, such as bonds, you can provide your clients with added security, which in turn can give you peace of mind. Although it may appear daunting at first, it is important to recognize the significance of these measures.
Why are surety bonds important?
Larger government agencies and clients often require proof of a surety bond before they will work with your business. State laws also mandate bonds for certain professions.
It’s a key part of risk management when businesses take on big projects. Even the most reliable business could unexpectedly lose money if they can’t fulfill their obligations. To guarantee that your client won’t lose money, surety bonds provide a supply chain disruption or if valuable materials run out or if a valuable employee suddenly leaves.
When your small business is not required to have a commercial surety bond, it can be a reliable way to prove your reliability. This can give you an edge over non-bonded competitors, as it could make the difference between winning or losing a project.
You may need a surety bond to:
How much do surety bonds cost?
The cost of a surety bond is $8 per month for Insureon customers, on average. Construction companies typically pay a higher rate.
Variables that impact the expense comprise:
Other common questions about surety bonds
How do surety bonds work?
Small standard insurance policies, such as surety bonds, do not cover work like policyholders’ claims. Surety bonds, on the other hand, pay out claims to the obligee (also known as the client). For example, if your small business fails to complete a construction project, the surety company will reimburse your client.
A surety bond is similar to an insurance policy, but it functions more like a line of credit. Instead of paying the back amount to the bond surety company or insurer, you are required to pay this amount back, just like you would with a line of credit, unlike an insurance policy.
If your business fails to adhere to regulations or breaks the terms of a contract, the insurance company will reimburse your client. In order to provide financial guarantee, a surety bond is offered for the project.
When do you need a surety bond?
Before you begin working with a client, they may ask you to purchase a specific amount of surety bond, based on their own premises. State laws often require professionals in certain professions to obtain a surety bond or license before they can legally work.
For example, you may need a surety bond to sign a construction contract, or work for your local government on a project.
If you do not meet the contractual obligations, you can rest assured that they will be willing to work with your company, even if it is a relatively new business. This means that surety bonds protect your clients from financial loss.
You’ll need to study the regulations in your state to ensure that you have all the required guarantees and insurance for your occupation. You can also seek advice from an insurance broker who can assist you in locating the appropriate coverage.
How do you get a surety bond?
What’s the difference between being licensed, bonded, and insured?
Feedback from our clients.
“Excellent efficient procedure. Fast, simple, and assistance is extremely beneficial.”
Ryan F.
System integration.
Denise Smith is a breath of fresh air. I loved every second of dealing with her. Yes, I’m talking about buying insurance and Denise Smith is a breath of fresh air. Denise made the insurance buying experience exceptional, but most people don’t love that. She is a rock star.
Kristine W.
Production of food items.
“We required quotations quickly and coverage even more quickly. We obtained both. We value your assistance. THANK YOU.”
Discover insurance quotes for small businesses.
Save money by comparing complimentary quotes from highly-rated insurers.